St George Island Top Mistakes Investors Make in 2026 — And What to Do Instead
St. George Island keeps showing up on investor radar for good reason. It’s a barrier island with genuinely limited land supply, pristine Gulf beaches, and steady tourism demand from families, anglers, and nature travelers. But here’s the honest truth — the st george island top mistakes investors make aren’t subtle. They’re the same five or six errors that show up over and over, and they cost real money. At Rent & Relax Vacation Rentals, we manage an active portfolio on the island and pull live Key Data market intelligence every month. We see what works and what blows up a pro forma. Right now, with 219+ active listings, average days on market stretching to 121–155 days, and a 94% sale-to-list ratio giving buyers roughly 6% negotiating room, prepared investors have a genuine window. But only if they avoid the traps below.
Why St. George Island Attracts Investors — And Why That Creates Risk
The Island’s Core Investment Appeal
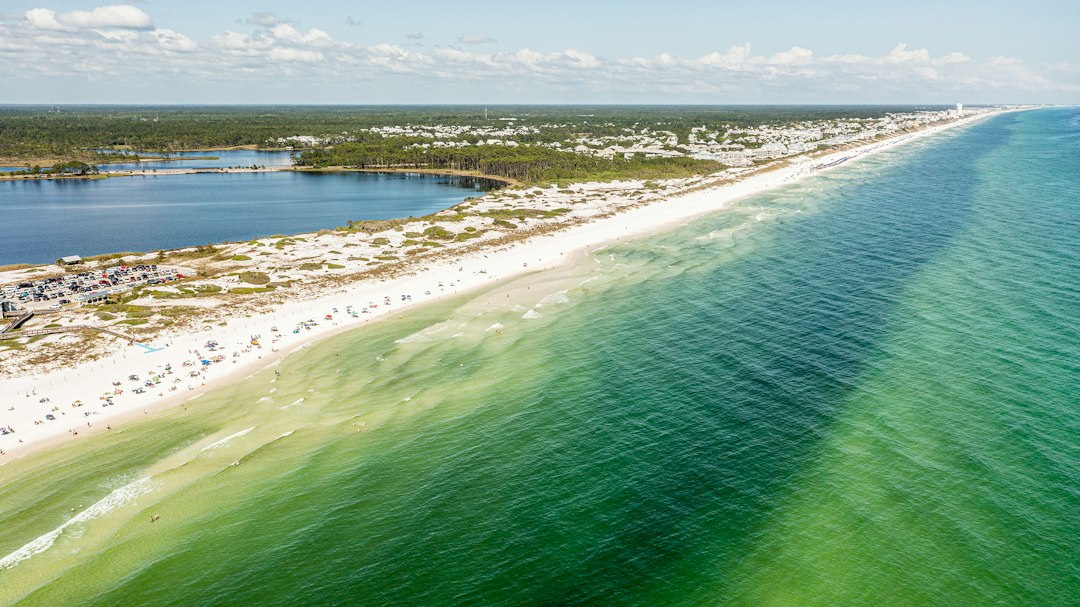
The geography is the pitch. St. George Island is a 28-mile barrier island in Franklin County — you cannot build more of it. That limited supply, combined with tourism-led demand from families and outdoor recreation visitors, gives the investment thesis real legs during peak season.
Strong demand windows run late spring through summer, holiday weeks (Thanksgiving, Christmas, New Year’s, spring break), and the early fall shoulder season when Gulf water temperatures stay warm. Those windows drive the revenue math.
But here’s the catch: there is no major year-round employment base on St. George Island. The entire investment thesis lives or dies on vacation demand. And emotional buyers — people who fall in love with the lifestyle — often let that feeling overrule the numbers. That’s where trouble starts.
What the Current Market Actually Looks Like in 2026
The headline numbers tell a complicated story. Median listing price sits around $1.15 million per Realtor.com data. Median sold prices range from approximately $935,000 (local MLS commentary, August 2026) to $1.23 million (Homes.com trailing 12-month figure) — depending on who’s measuring what and over which period.
Active inventory sits at roughly 219–221 listings with about 75 reported price reductions. Average days on market runs 85 days per Realtor.com, and 121–155 days per Homes.com and local MLS commentary. The sale-to-list ratio is approximately 94%, meaning buyers are routinely getting 6% off asking price.
No foreclosures. No short sales. This isn’t distress — it’s a market that has normalized after several years of compressed inventory. And that normalization is creating the best negotiating environment investors have seen in years. But only buyers who avoid the following mistakes will actually capture it.
Mistake #1 — Trusting Headline Market Numbers Without Comparing Like-for-Like Properties
Why St. George Island Data Is Unusually Misleading
This one tops the list of st george island top mistakes investors make because the numbers look clear until you dig in. Redfin reported a 37.7% year-over-year price increase for the three months ending August 2026. Homes.com reported prices essentially flat over the trailing 12 months. Both figures are technically accurate. They measure different things over different periods in a small, high-variance market.
The broader 32328 ZIP code includes Eastpoint on the mainland — a completely different market. Local MLS data for that ZIP showed listings jump from 103 to 261 between June 2025 and May 2026, while the median sold price dropped from $1.1 million to $664,900 over the same stretch. That collapse in median price isn’t a St. George Island story. It’s a mainland contamination problem in the data.
A handful of Gulf-front sales can shift the island-only median by six figures in either direction. This is a thin, heterogeneous market. Averages lie here more than almost anywhere else along the Emerald Coast.
What Smart Investors Compare Instead
Stop comparing island-wide medians. Start comparing properties that will actually compete with the one you’re underwriting.
Beach access type matters enormously. Gulf-front, Gulf-view, and second-tier lots each command materially different Average Daily Rates and occupancy. A Gulf-view property is not a Gulf-front property, and your pro forma shouldn’t treat them the same.
The physical features that drive rental revenue on this island: private pool, elevator, bedroom count, pet policy, view corridor, and parking availability. A four-bedroom Gulf-front home with a private pool should never be benchmarked against a three-bedroom bay-side condo.
Always request verified rental history from the prior owner or property manager — not a platform estimate. And before any offer, get the flood zone designation, elevation certificate, and insurance quotes specific to that parcel. Insurance on St. George Island can be a deal-killer on properties that look fine on paper.
Actionable step: Request a full rental history report and a current elevation certificate before making any offer. If the seller can’t produce both, that tells you something.
Mistake #2 — Underwriting Revenue Based on Market Averages Alone
This is the financial core of the st george island top mistakes investors make conversation — and it’s where the most expensive errors happen.
What Our Managed Portfolio Data Shows Right Now
According to current Key Data market intelligence pulled from our Rent & Relax managed properties in October 2026:
- Average Daily Rate (ADR): $307.41 — down 20% from the prior year. For buyers, that means purchase prices haven’t fully caught up to the ADR reset. You’re entering at a point where the premium baked into prior-year valuations is deflating.
- Adjusted Paid Occupancy: 42.7% — down 15.3% from the prior year. Same logic applies. This is a favorable market entry point, not a red flag.
- RevPAR: $104.15
- Average Booking Window: 45 days in advance
- Average Length of Stay: 5.2 nights
Market-level benchmarks from competitor data (via AirROI and independent market reporting) show a directional ADR around $520, median ADR near $470, and top-decile ADR at $911 or more. Average annual revenue per listing is estimated at approximately $49,847. Collins Vacation Rentals — the island’s longest-running operator since 1973 — manages roughly 275–280 homes. Resort Vacation Properties (now Vacasa) manages over 300. Those operators represent a large share of professionally managed supply and give you useful competitive context.
The gap between our managed portfolio ADR ($307.41) and the broader market directional ADR ($520) reflects a mix of property types and management strategies. Premium Gulf-front homes with pools and elevators will outperform. Smaller interior units won’t. Underwrite the specific property, not the market average.
How to Build a Realistic Pro Forma
Using $49,847 in gross annual revenue as a baseline (the reported market average), here’s a straightforward stress test:
- At a $1.0 million purchase price with a 35% expense ratio, your net operating income is roughly $32,400 — a 3.2% cap rate.
- At a $1.2 million purchase price with the same expense load, that cap rate drops to approximately 2.7%.
Those aren’t bad numbers for a barrier island asset with appreciation potential — but they’re tight. And that expense ratio needs to actually include: professional management, cleaning and turnover, repairs, utilities, insurance, property taxes, HOA or condo dues, pool and elevator maintenance, storm reserves, platform fees, and furniture replacement cycles. Investors who undercount expenses by 10% can turn a marginal deal into a money-losing one inside 18 months.
Mistake #3 — Ignoring Insurance, Flood Zone, and Carrying Cost Realities
St. George Island is a barrier island. That phrase should trigger a specific checklist before you write any offer — and many investors skip it entirely.
Flood zone designation and elevation certificate are non-negotiable pre-offer items. Two properties sitting one street apart can have dramatically different insurance costs based on their FEMA flood zone and base flood elevation. We’ve seen investors underwrite a deal using generic insurance estimates and then get the real quotes back after going under contract. The numbers can swing by $15,000–$30,000 per year or more on a Gulf-front property.
Windstorm and hurricane coverage is a separate line item from standard homeowners. Citizens Insurance or private market alternatives — both have specific underwriting requirements on barrier islands that mainland buyers aren’t used to seeing.
Also verify Franklin County zoning, coastal construction setback requirements, any active beach renourishment or erosion management plans, and the status of the St. George Island Water and Sewer District for your specific parcel. These are not deal-breakers by default — but they’re budget items that have to be in your numbers before you close, not after.
Mistake #4 — Skipping the Short-Term Rental Rule Check
This one is quick but critical. St. George Island and Franklin County have specific rules around vacation rental licensing and occupancy. HOA and condominium documents in some complexes restrict short-term rental activity in ways that aren’t obvious from the MLS listing. We’ve talked to investors who closed on a property and then discovered their target rental model was restricted by the condo association.
Read the docs before you make an offer. Confirm vacation rental licensing requirements with Franklin County directly. If there are active proposals to change short-term rental regulations — and that information may not appear in a standard MLS search — you want to know before you close, not after.
Mistake #5 — Buying Without a Management Strategy in Place
The 45-day average booking window on St. George Island (per current Key Data market intelligence, October 2026) means guests aren’t planning six months out. They’re booking 45 days in advance. Your pricing, availability, and marketing have to be positioned for that behavior — not set once and left alone.
Investors who close without a professional management relationship in place tend to underperform for the first full season while they figure out operations. That’s lost revenue you can’t recover. The 5.2-night average length of stay means your cleaning and turnover schedule has to run efficiently or your per-booking economics fall apart fast.
A property manager with active presence on the island — one pulling real market data, not guessing at pricing — is not a cost center. It’s a revenue driver. The management fee pays for itself when your occupancy and ADR are optimized from day one.
Frequently Asked Questions
What is the average occupancy rate for St. George Island vacation rentals?
Our Rent & Relax managed properties are running 42.7% adjusted paid occupancy as of October 2026 per current Key Data market intelligence. Broader market estimates directionally imply approximately 26% annual occupancy based on reported average revenue and ADR figures — though that calculation includes off-market and owner-use periods. The strongest occupancy windows are late spring through summer, major holiday weeks, and early fall. Actual performance depends heavily on beach access type, bedroom count, pool, and pricing strategy.
What should I expect to pay for a vacation rental investment on St. George Island?
Median listing prices are running around $1.15 million as of 2026. Median sold prices range from approximately $935,000 (local MLS August 2026) to $1.23 million (trailing 12-month Homes.com figure). The 94% sale-to-list ratio means buyers are averaging about 6% off asking price, and with 121–155 average days on market, there is genuine negotiating room — particularly on properties with price reductions already in place.
Is St. George Island a good market for vacation rental investment right now?
The current entry conditions — more inventory, longer days on market, and ADR that has reset from peak levels — create a more favorable buying environment than investors have seen in several years. The key is underwriting the specific property correctly: verify rental history, get real insurance quotes, confirm flood zone, and build a conservative expense model. Don’t rely on market averages to justify a specific purchase price.
How do I find out what a specific St. George Island property has actually earned in rental revenue?
Request the verified rental history directly from the seller or their current property manager. Platform estimates (AirDNA, Mashvisor, etc.) provide directional benchmarks but are not a substitute for actual booked revenue history on a specific address. A good property manager can pull comparable performance data for similar homes on the island to cross-check whatever the seller provides.
What are the biggest hidden expenses investors miss on St. George Island?
The most common blind spots: windstorm and flood insurance costs specific to the parcel’s flood zone and elevation, pool and elevator maintenance on Gulf-front homes, storm reserves, annual furniture and appliance replacement cycles, and platform fees. Many first-time investors also underestimate cleaning and turnover costs on a 5-night average stay with a tight changeover schedule. Budget a 35–40% expense ratio and stress-test your numbers at both ends before closing.
Ready to Invest in St. George Island?
If you’re serious about buying a vacation rental on St. George Island, the current market gives you more room to negotiate than you’ve had in years. But the numbers only work if you go in with accurate data, realistic expenses, and a management strategy that starts generating revenue from week one.
At Rent & Relax Vacation Rentals, we manage 100+ properties along Florida’s Emerald Coast — including an active St. George Island portfolio. We pull live Key Data market intelligence every month and can show you exactly what comparable homes are earning right now.
Contact us before you make an offer. We’ll walk you through the real numbers, flag the red flags, and help you underwrite a deal that actually pencils out. Reach out to the Rent & Relax team today to get started.