Cape San Blas Gulf Front vs Gulf View ROI: Which Investment Actually Pays Off?
Here’s the situation a lot of buyers find themselves in right now. You’re looking at two Cape San Blas vacation rental properties — same bedroom count, same zip code, both a short walk or less from the water. One is priced at $875,000. The other is $1,200,000. The difference? One sits with sand at the bottom of the steps. The other has a Gulf view and a short walk to a deeded beach access.
That $325,000 gap is real money. And the question of whether it actually comes back to you in rental income, appreciation, or both is not as simple as it sounds on the Panhandle.
In most Florida beach markets, Gulf front wins. Full stop. But Cape San Blas plays by slightly different rules — land scarcity, low-density zoning, a narrow peninsula profile, and a guest base that skews toward families who book long stays and come back every year. Those factors change the math. Current Key Data market intelligence (August 2026 pull) across our managed properties shows an ADR of $306.21 and adjusted paid occupancy of 47.7%. Both figures reflect a market that has softened from prior-year peaks — which is exactly the environment where knowing which property type generates stronger returns matters most. Buy the wrong asset class in a compressed-margin market and you’ll feel it.
This post breaks it all down: purchase price differential, revenue potential by property type, cap rate ranges, long-term appreciation factors, and which type of buyer each option actually serves best. Let’s get into it.
Understanding the Price Gap — What You’re Actually Paying for at Cape San Blas
Current Cape San Blas Pricing by Property Type
The 2025 MLS year-in-review for Cape San Blas puts the average residential sale price at approximately $1,034,278 and the median at approximately $821,000. Realtor.com snapshots show a broader median in the $445,900–$664,950 range depending on the data pull and product mix. Median price per square foot runs approximately $357–$387 across the Cape.
Break that down by tier and here’s what it looks like in practice:
Gulf front homes on Cape San Blas — true beachfront, no road between the structure and the sand — are clustered at or above $1.0M to $1.5M for modern STR-ready builds with private boardwalks, pools, and open-concept layouts designed to photograph well and sleep large groups. Luxury new construction pushes higher.
Gulf view and second-tier properties more commonly land in the $650,000–$900,000 range. Older or smaller stock can fall closer to the broader Cape median. Same general neighborhood, meaningful price difference.
The realistic gap between a true Gulf-front home and a comparable Gulf-view home on the Cape is 20–40% — often $200,000 to $400,000 or more depending on lot width, year built, pool presence, and whether there’s private beach access. That delta is what you need to close with rental revenue, appreciation, or both before Gulf front makes more financial sense than Gulf view.
What “Gulf Front” and “Gulf View” Actually Mean on the Cape — and Why It Matters
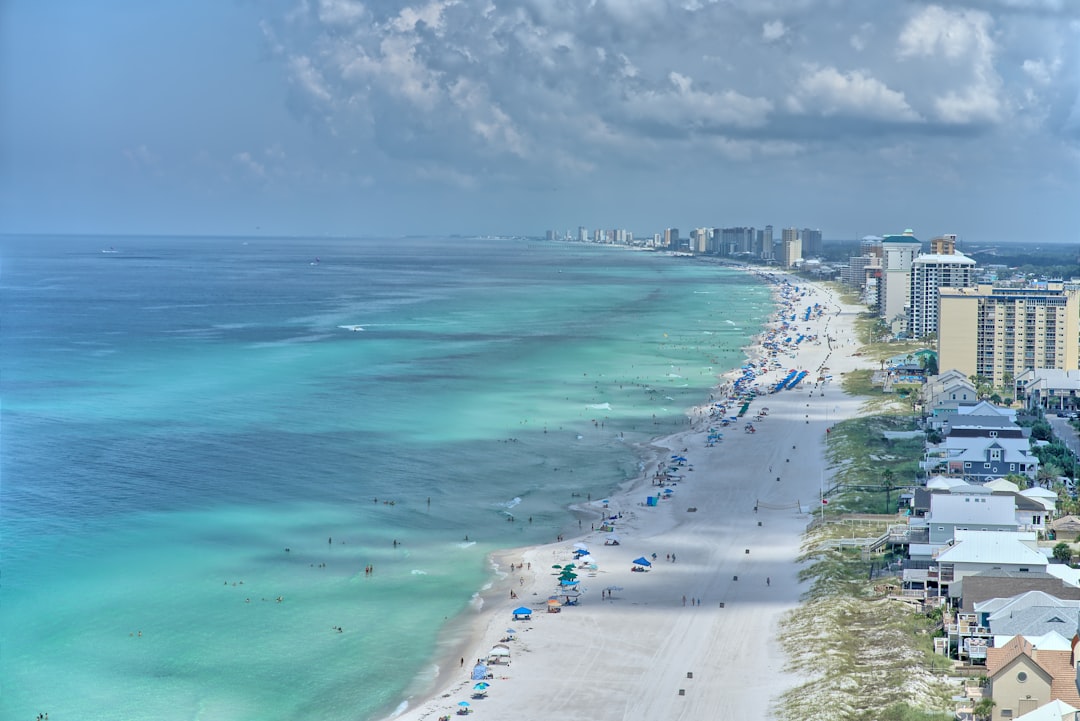
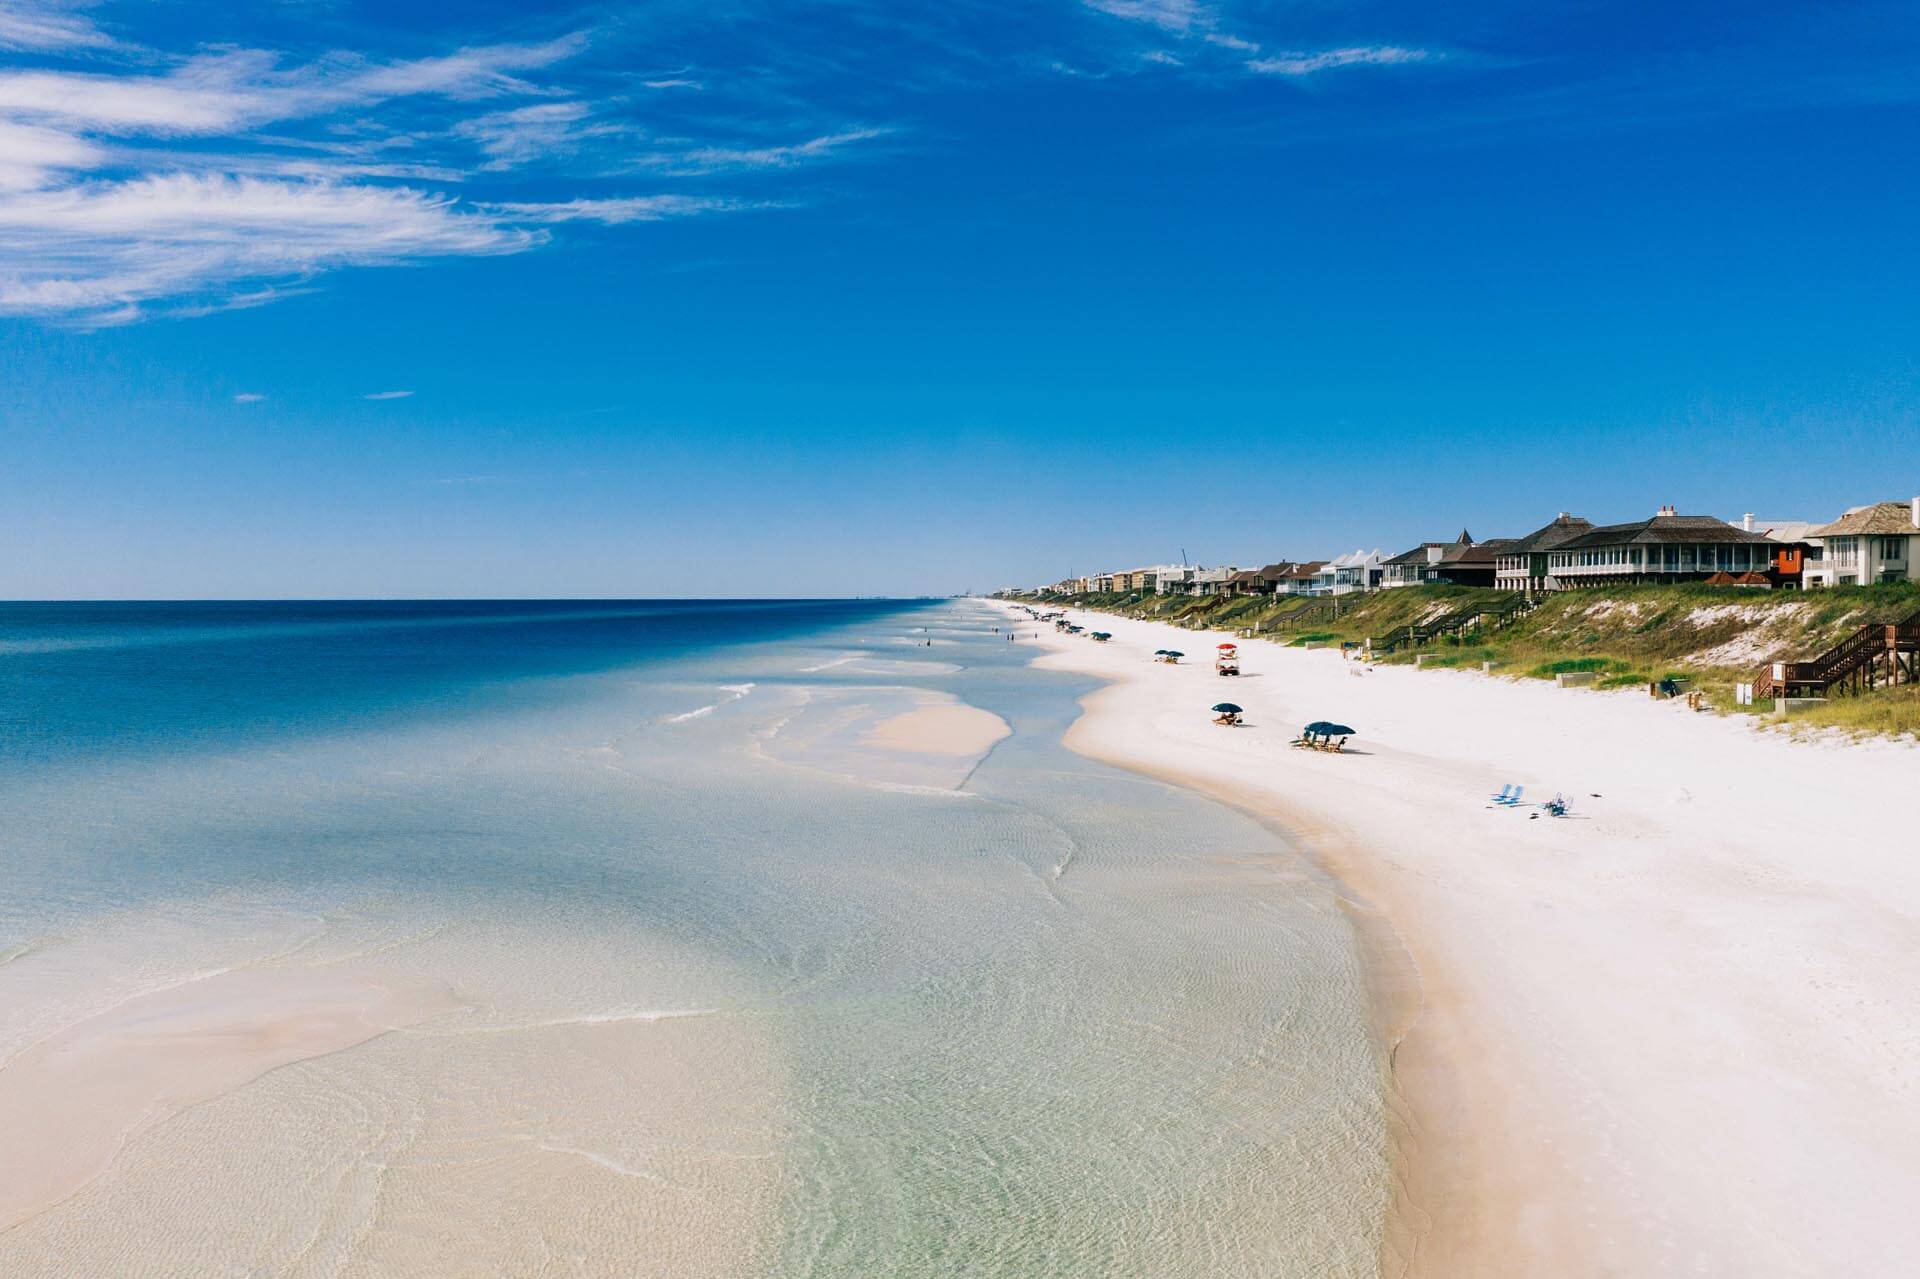
Before you model out any ROI, get the definitions right. Gulf front means direct beachfront — the home sits on the Gulf side of the road with no other structure or public road between it and the water. Guests walk out the door and they’re on the beach. Gulf view means the home sees the water, but there’s a road, a dune line, or a row of other homes between it and the sand.
Here’s where Cape San Blas gets interesting. The peninsula is narrow. Genuinely narrow. Some Gulf-view properties on the Cape are a two-minute walk to beach access — deeded, well-maintained, and easy to find. That’s a different experience than a “Gulf view” home in a dense market like Destin where the beach might be a shuttle ride away.
For vacation rental purposes, the experiential gap between a Cape Gulf-view home with easy beach access and a Cape Gulf-front home is smaller than it would be in most Panhandle markets. Renters notice. And because renters notice, the revenue gap narrows — which is central to understanding why Gulf view can be a genuinely competitive investment on the Cape.
One more thing worth flagging here: older Gulf-front stock without pools, without modern open floorplans, and without elevator access can actually underperform a strategically updated Gulf-view home with a pool, pet-friendly policies, and solid photography. Location matters, but amenities close the gap fast in the Cape San Blas rental market.
Days on Market and What It Means for Negotiation
The Cape San Blas market has slowed down significantly. Average days on market ran approximately 36 days in 2022. By 2024, that stretched to approximately 107 days. In 2025, it hit approximately 142–151 days for residential properties. Realtor.com snapshots show median DOM in the 74–123 day range with 767–880 active listings depending on the pull date.
That is not a crisis — it is a buyer’s window. The Cape is no longer a blink-and-miss-it market where Gulf-front homes get multiple offers before the open house. Buyers now have time to negotiate, inspect thoroughly, and pressure-test every line of the pro forma before committing. Dated Gulf-front homes without pools, without elevators, and without rental-optimized layouts are sitting. That creates real leverage if you know what you’re buying and why.
Vacation Rental Revenue — How Gulf Front and Gulf View Actually Perform
Cape San Blas STR Benchmarks: Two Data Sets, Clearly Labeled
Two data sources here, and it’s worth being direct about what each one represents.
Our managed properties (current Key Data market intelligence, August 2026 pull):
- ADR: $306.21
- Adjusted paid occupancy: 47.7%
- RevPAR: $115.30
- Average booking window: 43 days in advance
- Average length of stay: 5.2 nights
Both ADR and occupancy reflect a favorable buyer entry point compared to prior-year peaks. Softer metrics at the market level mean you can acquire at a better price point and build a rental strategy around current, realistic numbers rather than 2022 peak projections that no longer exist.
Market-wide competitor data (AirROI, Cape San Blas peninsula proper, independent owners and competitor-managed listings):
- Market ADR: approximately $566
- Peak ADR (June–July): approximately $610–$614
- Blended occupancy (Airbnb + Vrbo): approximately 54%, with approximately 4% year-over-year growth
- Approximately 87 active Airbnb listings sampled; $42,133 average annual revenue; 32.4% occupancy; $195 RevPAR
The ADR difference between these two data sets reflects different property mixes and methodology — not a discrepancy to worry about. Use both to bracket your expectations.
Gulf Front vs Gulf View: How the Revenue Actually Stacks Up
Across Cape San Blas, Gulf-front homes consistently command top-tier ADRs — typically 15–30% above a comparable Gulf-view home with the same bedroom count. They also fill the prime weeks first. March, June, July, and the first two weeks of August book early and at full rate on Gulf-front properties. That peak-week occupancy advantage compounds into meaningful annual revenue separation.
A well-run 4–6 bedroom Gulf-front home on the Cape in current market conditions can realistically generate $80,000–$130,000 in gross annual revenue. A strong Gulf-view home with a private pool, pet-friendly policy, deeded beach access, and solid management commonly lands in the $55,000–$90,000 range.
Now run those numbers against purchase price:
A $1,200,000 Gulf-front home generating $110,000 gross produces a gross yield of approximately 9.2%. A $850,000 Gulf-view home generating $75,000 gross produces a gross yield of approximately 8.8%. The gap is real but it is not dramatic — and it compresses further when you factor in higher insurance premiums, maintenance costs, and HOA fees that tend to be associated with direct beachfront properties.
Cap rate ranges on the Cape currently run approximately 4–6% for Gulf-front properties and approximately 5–7% for Gulf-view when the Gulf-view home is well-positioned and managed correctly. Gulf view wins on percentage yield. Gulf front wins on gross revenue and, historically, on appreciation. Which one matters more depends entirely on your financial structure and investment horizon.
Seasonality and What It Does to Your Annual Numbers
Cape San Blas is a summer-heavy market. Peak season in March, June, and July produces approximately 50.2% occupancy and approximately $575 ADR across the market. Low season — January, November, December — drops to approximately 22.8% occupancy with an ADR of approximately $513. That ADR holding relatively firm in the off-season is actually a Cape strength compared to other Panhandle markets.
The seasonality spread matters when comparing Gulf front and Gulf view. Gulf-front homes capture a larger share of the high-demand peak weeks, which is where the annual revenue advantage is built. Gulf-view homes are more dependent on shoulder-season bookings to close the gap — which means amenities, pricing strategy, and management quality matter even more for Gulf-view performance.
Our average length of stay across managed properties is 5.2 nights — that’s a family market, not a weekend-trip market. Guests coming to Cape San Blas are planning a real vacation. That benefits both property types, but it particularly helps well-positioned Gulf-view homes that offer the full family-vacation package at a lower nightly rate than Gulf front.
Long-Term Appreciation and the Case for Each Property Type
Why Gulf Front Wins the Appreciation Argument
They are not making more beachfront on a narrow Florida peninsula. That’s the entire argument, and it holds. Gulf-front lots on Cape San Blas are finite, they are increasingly difficult to insure and permit for new construction, and beach renourishment and dune protection projects along the Cape are actively working to preserve the wide-beach profile that drives premium pricing. Infrastructure improvements along Cape San Blas Road — including ongoing stabilization of the Stumphole area — reduce the historical storm-access risk that has historically suppressed values on the lower Cape.
Long-term, Gulf-front land appreciates in ways that second-tier properties do not. If your investment horizon is 10-plus years and you can handle the higher carrying cost, Gulf front builds equity in a way that is structurally difficult for Gulf-view properties to match.
Why Gulf View Makes Sense for More Buyers Right Now
Lower entry price means lower debt service, lower insurance exposure, and more room to absorb the market softening we are currently seeing. A buyer who puts $850,000 into a well-positioned Gulf-view home with a pool and easy beach access today, in a market with 142-plus days on average DOM and real negotiating leverage, is entering at a point that makes the cash-flow math work. The percentage yield is higher. The risk profile is lower. And the STR-friendly zoning on the Cape — focused on safety, septic, and parking rather than outright rental restrictions — means the operational environment remains open.
Cape San Blas continues to market itself as a low-density, family-oriented destination. That is a meaningful differentiator from Panama City Beach or even parts of 30A. It attracts guests who return annually, book longer stays, and treat the property with more care. That demand profile supports Gulf-view performance in a way that a more transactional beach market would not.
Frequently Asked Questions
Is a Cape San Blas Gulf-front home worth the premium for vacation rental income?
It depends on your price point and holding period. Gulf-front homes on Cape San Blas generate 15–30% higher ADR than comparable Gulf-view homes and capture peak weeks more consistently. A well-run 4–6 bedroom Gulf front can gross $80,000–$130,000 annually in current market conditions. But that premium comes with a higher purchase price — often $200,000–$400,000 more than a comparable Gulf-view property — plus higher insurance and maintenance costs. On a gross yield basis, Gulf view often competes closely. On long-term appreciation, Gulf front has a structural advantage.
What’s the realistic cap rate range for Cape San Blas vacation rentals right now?
Based on current market pricing and revenue data, Cape San Blas Gulf-front properties are producing cap rates in approximately the 4–6% range. Gulf-view properties with pools and good beach access are running approximately 5–7%. Both ranges reflect the current softening in ADR and occupancy — which also means you are buying in at a better price point than you could have achieved in 2022 or 2023.
How does a Gulf-view Cape San Blas property close the revenue gap with Gulf front?
Three things close the gap: a private pool, a pet-friendly policy, and easy beach access (deeded or short walk). On the Cape, the narrow peninsula means some Gulf-view homes are genuinely close to the water. Guests who can’t afford Gulf-front rates will happily book a Gulf-view home that delivers the full family-vacation experience at a lower nightly cost. Longer stays at strong rates add up. The gap is real but it is closeable with the right property and the right management approach.
Is Cape San Blas still short-term-rental friendly in 2026?
Yes. As of current reporting, Cape San Blas has not implemented sweeping STR bans or restrictive licensing frameworks. Regulations focus on safety, septic systems, and parking compliance rather than restricting nightly rentals. This is a meaningful contrast to parts of 30A and other Panhandle markets where STR regulations have tightened significantly. Cape San Blas remains a strong operating environment for short-term rental investors.
With days on market at 142+ days, is Cape San Blas overbuilt or just slow?
It’s a slower market, not a broken one. Investor interest remains strong and a sizable share of Cape properties are considered equity-rich. The longer DOM reflects broader macro headwinds — higher insurance costs, rising rates, and a normalization of demand after the pandemic surge — not a structural problem with the Cape as a destination. For buyers, extended DOM means negotiating leverage, especially on dated Gulf-front stock that lacks pools or modern rental layouts. That’s a strategic entry window, not a red flag.
Ready to Invest in Cape San Blas?
Whether you’re running the numbers on a Gulf-front home at $1.2M or a well-positioned Gulf-view property at $800,000, the decision comes down to your yield targets, your holding period, and how you plan to operate the asset. We manage 100-plus vacation rentals along Florida’s Emerald Coast — including Cape San Blas — and we can show you exactly what properties like the one you’re considering are actually producing right now, not what they produced in 2022.
Contact Rent & Relax Vacation Rentals today. We’ll walk you through real revenue data from our managed portfolio, help you evaluate specific listings, and put together a pro forma grounded in current Key Data market intelligence — not wishful thinking.
Call us, email us, or fill out the inquiry form on our website. If you’re serious about Cape San Blas, let’s sit down and look at the actual numbers together.